Slide 1

South Florida’s Exclusive Buyers Agent

Slide 2
For over 40 years

International investors

COVID-19 Real Estate Home Buying Process
Real Estate Process
Real Estate Process

COVID-19 Real Estate Home Buying Process
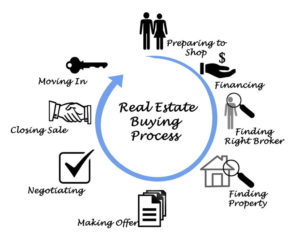
With the current COVID-19 pandemic, the federal government has labeled residential and commercial real estate as an essential business. Yet, COVID-19 has changed how real estate is conducted not only with how Realtors are showing properties but also how real estate transactions are closed.
One thing is certainly sure: being an “essential” business does not necessarily mean business as usual.
Pre-Closing
The New National Association of Realtors (NAR) guidelines follow and strictly adhere to all CDC safety guidelines. NAR supports and encourages that all brokerage firms order their agents to shelter in place and avoid all social interaction.
Such stay at home mandates and social distancing regulations have pushed real estate agents to become creative. Instead of having open houses, real estate agents are using virtual property showings, and Facebook live open houses. There are programs for customers to even design their home using digital tools, watching videos of the construction as their property is being built. Realtors are doing initial showings over video chat services like Face Time, Skype or Zoom.
Contract
Perhaps the real challenge COVID-19 poses to home buying is not necessarily shopping for the home—rather, it is closing on one.
Issues with contracts focusing on force majeure clauses, or clauses that provide for a delay or opportunity to get out of underlying obligations in the event of unforeseen or uncontrollable events have been an emerging issue during this pandemic.
The development of the COVID-19 Extension Addendum to Contract allows for time periods and dates to be extended as a result of the Corona-virus pandemic.
Closing
Once contract issues are overcome, the closing itself has evolved due to this crisis.
Make sure that you or the Seller only use an escrow and Title company that is capable of handling the closing. Specifically ask whether they use online or mobile notaries. Also determine if the local recorder’s office uses electronic recording and whether the title company is equipped to record the deed electronically.
Many documents in the closing process require a notary, and notarization is normally required to be done-in person. The Florida legislature and Governor signed into law effective January 1, 2020, a new law that allows for what is called remote online notarization (RON). This is a huge game-changer in the State of Florida, particularly in the area of real estate closings. No longer do parties all have to get together at a certain set time around the conference room and execute documents. Now, from the comfort of your own home, provided that you have your own laptop or smart phone, you can execute documents online and remotely and have those documents notarized. While the technology is new, it is not that new. It is the same technology that is used to validate your passport or driver’s license when you go through security at an airport. This validation technology is now being used for remote online notarization (RON).
If, for example, you are in another state and are closing on real estate located in Florida, or, perhaps, you are in a profession (such as being a doctor and on call) that makes it difficult to attend a closing, you can now remotely video into the closing and notarize your documents from the comfort wherever you might be. Documents are produced online for your review, and at the point that you are prepared to execute those documents, you can do so remotely. A notary is present at the time online, not physically with you, and that notary is then able to confirm and validate that you executed the documents without any duress or coercion.
There is a caveat, however, and that is that while remote online notarization, in theory, should work all over the world, it really is more of a domestic service for people within the United States. It is difficult for the technology, at this stage, to validate foreign credentials.
Appraisals and home inspections are other aspects of residential real estate closings are evolving during this pandemic. The Federal Housing Finance Agency is allowing alternative appraisal methods such as “drive by” appraisals where appraisers drive through the neighborhood and walk around a property without going into it. They are also doing “desktop” appraisals using public data to generate property values.
The loan process will likely take longer than in the past and I am encouraging my buyers to agree to no less than a 60 days closing if a loan is needed. You need to take this into consideration with your home buying timeline if you need to close on a property by a certain date.
Moving during a Pandemic
 I recently published an entire BLOG article on this subject which you can read here along with other articles that you may find informative.
Tips for Buying a Fixer-Upper

Fixer-uppers have long had their fans. Some investors love the idea of making major repairs that increase a home’s value and then reselling the property for profit. Others want a low-priced starter home and don’t mind making gradual improvements over time.
Buyers must do their due diligence so that they understand their total investment in the property and the cash requirements; since most repairs cannot be financed. An Exclusive Buyer Agent’s goal is to help buyers avoid making expensive mistakes.
While repair issues, un-permitted work, or liens might not derail a sale on its own, they warrant a call to an expert who can assess the problem, offer solutions or give repair estimates.
Warning Signs Before Purchasing a Fixer-Upper:
  1. Consider the amount of time and the amount of cash you have to address obvious deficiencies with the property.
  2. Does the property smell damp? From mold to warping, moisture can cause considerable damage to homes, even making them uninhabitable. The first clue is that moisture smells. Besides damage to the house, moisture can adversely affect a homeowner or tenant’s health.
  3. Stuck windows and doors. These can also be a sign of moisture or that a house is settling due to age or structural shifting. Both are problematic.
  4. Sloping or sagging floors. Both indicate structural problems beyond just aging. Buyers should find out if framing, joists or sub-flooring need replacement.
  5. Foundation problems. One small crack can be just the beginning of many cracks and can signal that a house could eventually crumble.
  6. Inward grading, poor drainage and short downspouts. Improperly installed or clogged gutters and downspouts all may cause water to enter a house.
  7. Bad roof. An old roof may leak but it’s not always the shingles or tiles that are the culprit. Sometimes, it’s what’s underneath – sheathing, trusses, beams and rafters. The sellers should disclose when the roof was installed.
  8. Outdated wiring and fuses. Because homeowners rely on so much technology today, outdated wiring may, in worst cases, start a fire. Often, dated electric boxes make the home un-insurable.
  9. Outdated plumbing. Toilets that don’t flush properly, sinks and showers that lack adequate pressure or have leaks, and water heaters that don’t provide enough hot water signal a need for attention. Not to mention the condition of the pipes from the home to the street.
  10. Termite damage and wood rot. Buyers may spot blisters in wood flooring, hollow sections of wood, and even the bugs themselves. An exterminator can determine the extent of the damage and estimate repair costs.
  11. High energy bills. This should alert buyers to the cost of cooling the home. Due diligence can tell them whether their Ac handlers, insulation, or doors and windows are inefficient and need to be sealed, repaired or replaced.
  12. Historic home designation and zoning rules. Municipal guidelines may restrict buyers from making certain improvements to their home and property.

Tips for Condo Buyers

South Florida Condominium
Buying a condo, short for condominium, can be a great way to dive into home ownership without worrying about much of the upkeep that comes with single-family homes and townhouses. Condo dwellers can also typically take advantage of shared amenities, plus having professional management to take care of building maintenance.
However, condos aren’t for everyone so it’s best to figure out what your lifestyle and budget needs are first.
Whether you are purchasing a vacation condo or making South Florida your permanent home, there are a few tips and tricks you should use to help make the condo buying decision easy and stress-free.
Here are just a few South Florida condo-buying tips to help you find your dream condo.
A condo is typically a shared piece of property with individual owners of each “unit” or condo. In most cases, condominiums offer services such as, but not limited to, fitness centers, tennis courts, and pools. Many people purchase condos due to less hands on maintenance and they enjoy lifestyle of living in a condominium community.
When buying a condominium, it is important you know that every condominium community is different. It’s crucial to know each community will have their own community rules, association fees, management company, and amenities.
Financial Strength
Take a close look at the health of the association just as closely as you do the unit itself. Associations should have reserve funds to maintain the parking lots, roofs, painting , pool and other maintenance items. If there are not enough funds to pay for the repairs, it would require a loan to the association which would be paid in monthly installments or a special assessment where all owners would have to pay their portion of the repair upfront. You should take this monthly condo association fee into consideration when planning to budget for your new home. If the association is not financially healthy, you will need to prepare to pay for unexpected expenses out of your own budget.
Building Style
The style of the building in which your condo is located in can impact your financial costs over time. Garden-style buildings have lower maintenance costs than towers. Multi-story buildings and towers have elevated costs associated with maintaining the elevator systems. The number of units and the size of the units within the association will also affect your maintenance dues. A larger number units divide the fees up between more people, lowering the cost than if you had a smaller amount of units .
Insurance
Depending on the exact location in South Florida, the cost of insurance varies. Research insurance costs and availability before signing the contract for your new condo. Beaches that are located on barrier islands offer additional challenges to obtain traditional all-perils insurance policies for both the association and the condo owner.
Beach Access/Condition
If you want to purchase a condo on the beach, you’ll need to consider the quality of the sand, the condition of the natural elements such as the dunes, and the width of the beach. Beach erosion is a common problem in Florida, especially after hurricanes and tropical storms hit. Take a deep dive into the history of the beach erosion and maintenance in the area you are looking to purchase your condo in. You certainly don’t want to purchase a condo on a beach that is eroding or isn’t properly maintained.
Mortgages and Financing
Financing a condo is not the same as financing a single-family residence. While it’s critical to get approved for a loan whether buying a condo or a house, obtaining financing can be trickier for a condo purchase, because many lenders don’t allow purchases of condos. Many condos are purchased with cash because of the regulations lenders and programs place. If you are looking to get an FHA loan, you’ll need to first make sure the condo community is on FHA’s approved list of communities. FHA typically requires that 80% of the units in the building are owner-occupied, so before you have your heart set on a property, double-check that it is on the approved list.
You can also obtain a private mortgage to purchase the condo, but this comes at a much higher price tag since many private lenders require a minimum of 20% down payment.Mortgages for condos may involve some additional steps. For condos, the condo association/complex must also be approved for a full loan approval to be issued, This may require additional paperwork, approval from the condo association, and even some additional costs paid before closing. You may need to make a bigger down payment or have extra cash in the bank since Lenders sometimes have extra requirements for condo buyers.
Association Fees
One of the largest expenses, in addition to your mortgage, will be your condo association dues. “Condo fees generally cover the maintenance of the common areas, utilities such as sewer and trash, security, building insurance, reserves and external building maintenance, In addition, whether the fees are paid monthly, quarterly, or annually, you will still be required to pay property taxes and need to carry homeowner’s insurance to cover your contents and your internal structure. Prospective condo purchasers should find out how much you will pay in monthly condo dues and what the fees cover within the community. Do these fees seem reasonable in return for the maintenance and amenities that are offered?
Rules and Regulations
Condo ownership comes with rules. It’s important that you understand what your unique responsibilities are to the overall community and what rules the condo association has in place. When you are buying a condo in Florida, you are required by law to receive a copy of the Declaration of the Condominium or condo docs as they are more commonly known – this is mandatory regardless of whether you are buying a resale condo, key-ready condo, or a per-construction condo. These condo docs are registered with the State and can be over 500 pages in length.
The condo docs will contain lots of specific information, including details about the developer, the formation of the Home Owners Association (HOA) and related fees, plans of the buildings, floor plans for each unit and the all important Rules and Regulations of the condominium.
Some Important information that you look for in the docs or ask for from the Condo Association:
  • What exactly are your ownership and voting rights within the association?
  • What percentage of the common expenses are you be liable for – many units offer different floor plans of various sizes, with each one making up a percentage
  • What restrictions are in place regarding the common elements and your unit?
  • Is there planning in place for further units to be constructed? Â If so, how many and when?
  • Does the developer have any options NOT to complete any of the facilities or amenities?
  • Is there a history of resident complaints at the condominium?
  • Is the Condominium Association currently involved in any form of litigation?
  • Does the Condominium Association have reserved funds set aside for maintenance projects and future capital expenditures?
  • What about pets – are there ANY restrictions?
  • Can you rent or sell your condo without restrictions?
  • Are there any restrictions regarding family and friends using, staying with, or occupying the unit?
Know About Special Assessments
A special assessment is a large fee that is charged to help pay for a significant project within the condo community, such as a structural repair. These special assessments can raise your association fees for a certain period of time or require a one time payment to the Association.
Whatever your preferences, carefully consider your current and future lifestyle needs, plus your financial situation. Consult with a real estate professional who specializes in selling condos to show you the ins and outs of condo living throughout your home search and protects your interests during the buying process.

FIRPTA Withholding – Foreign Investment in Real Property Tax Act

Foreign Investment in Real Property Tax Act

FIRPTA (Foreign Investment in Real Property Tax Act) Withholding is the Withholding of Tax on Dispositions of United States Real Property Interests

The disposition of a U.S. real property interest by a foreign person (the transferor) is subject to the Foreign Investment in Real Property Tax Act of 1980 (FIRPTA) income tax withholding.

FIRPTA authorized the United States to tax foreign persons on dispositions of U.S. real property interests.

Persons purchasing U.S. real property interests (“transferee”) from foreign persons, certain purchasers’ agents, and settlement officers are required to withhold 15% of the amount realized.

Withholding is intended to ensure U.S. taxation of gains realized on disposition of such interests. The transferee/buyer is the withholding agent. If you are the transferee/buyer you must find out if the transferor is a foreign person. If the transferor is a foreign person and you fail to withhold, you may be held liable for the tax.

One of the most common exceptions to FIRPTA withholding is that the transferee (purchaser/buyer) is not required to withhold tax in a situation in which the purchaser/buyer purchases real estate for use as his home and the purchase price is not more than $300,000.  However, buyers should be aware that while they may meet the withholding exemption they are still responsible for the seller’s tax liability, interest and penalties should the seller not file a US income tax return to report the sale and pay any relevant taxes.

Note to Non-Resident Buyers – If you purchase property from a non-resident seller and an exception to FIRPTA withholding does not apply then you must ensure that FIRPTA is satisfied as part of the closing.  Check your settlement statement prior to closing where you should see 15% of the sales price withheld on the seller’s side of the settlement statement.  Request a copy of the withholding certificate from the closing agent and, if withholding was calculated, request a copy of forms 8288, 8288-A and front and back of cancelled check.  Retain these documents in a safe place along with your settlement statement and other closing documents.

Foreign Investment in Real Property Tax Act (FIRPTA) Withholding

U.S. Tax law requires that a non-resident alien who sells an interest in U.S. real property is subject to withholding, for tax purposes, of 15% of the gross sales price (i.e. $45,000 on a property with a sales price of $300,000). The withheld amount is required to be forwarded to the IRS, by the Closing Agent, within 20 days of the date of closing. These funds are held until the IRS is satisfied that all taxes due by the non-resident are paid. In order to apply for a refund you can either:-

File U.S. tax returns for each year that rental income was received, reporting all income and expenses; file a final U.S. tax return in the year following the year of sale, to report the sale and recover the balance of cleared funds. This process can take up to eighteen months depending on when, during the tax year, the property is sold.

File prior year tax returns (where required) plus an application for early release of cleared withholding on or before the date of closing. By making this submission, the 10% withholding remains with the Closing Agent whilst the IRS processes the Withholding Application and issues a Withholding Certificate for the cleared funds – usually around 90 days.

Please note that applying for and receiving a Withholding Certificate does not eliminate your requirement to file a final U.S. income tax return to report the sale transaction. In fact, when your final tax return is filed you may receive a further tax refund depending on the number of owners and length of time that the property was held.

In order to ensure a timely release of your funds it is extremely important that the following is obtained PRIOR to closing:-

Buyer’s names, address and SSNs – if U.S. Citizens

Buyer’s names, address and ITINs – if non residents

Or, if the buyers are non residents and do not have ITINs, the buyer’s completed Form W-7 (one per buyer) and authenticated copy of the picture page of their passport(s)

Without this information the Application for a Withholding Certificate and early refund will be rejected. We suggest that you request your Realtor prepare your sales contract contingent upon the buyers providing the above information.

Who’s responsible for FIRPTA withholding on the sale of U.S. property?

Foreign Investment in Real Property Tax Act (FIRPTA) was established in 1980 to ensure the withholding of estimated amount of taxes which may be due on the gain from the disposition or transfer of a U.S. real property interest from a foreign person.

If you purchase U.S. real property from a foreign individual or corporation then you are required to make sure that the seller pays any taxes due on the property.  The buyer must execute or have executed the correct forms including the sellers name, address and social security number or individual taxpayer identification number.  15% of the gross sales price must be withheld and submitted to IRS or held in escrow whilst an application for reduced FIRPTA withholding is timely filed and processed.

If the buyer does not take care of the withholding and the seller is a foreign entity who leaves without paying their tax then 15% will be taken from the buyer.

Most buyers are unaware that it is their responsibility to determine if the transferor/seller is a foreign person and subject to FIRPTA withholding.  In reality, the settlement agent (Title Company or Attorney) may be instructed to deduct the 15% and submit to IRS or hold in escrow whilst an application for reduced FIRPTA withholding is submitted to IRS for processing.

Types of Movers for Home Buyers

relocation


relocation

Moving to a new house, city or state is one of the most stressful things a person can go through. Even when everything goes smoothly, you’ll likely be exhausted when all is said and done. Whether it’s down the street or across the country, moving is a major task that requires much effort and coordination. For this reason, many people choose to hire a moving company, but knowing who to entrust your belongings can be a daunting task.

While you do have the option of going the DIY route when moving, things will be so much easier and more convenient for you if you hire professional movers instead. You’ll incur certain costs by doing so, but the help they can provide is worth it.

It’s also a common mistake to hire the first moving company you lay your eyes on in an ad. There are so many moving companies out there, but not all are created equal. The movers you should hire are legitimate ones with licenses, insurance and other vital considerations. You should also get quotes from at least three movers to determine the best deal. Ask for references and verifying credentials. And remember to never pre-pay for a move!

Local Movers

There are many kinds of moving companies depending on the type of move you’re looking to make. Some companies specialize in local moves and will have limitations on the distance they’re willing to travel. Local movers are great for small cross-town moves since they typically charge by the hour.

Long-Distance

If you’re moving across the country, you’ll want to find a long-distance mover. These movers have special licensing that allows them to operate across state lines and they typically charge a bulk rate based on how quickly you need to be moved and how many items you’ll be moving. In some circumstances, you may even need to move out of the country. International movers will help you pack and get your items overseas. These moving companies are usually prepared for immigration and customs issues.

Full-Service

If you want a completely stress-free move, you should consider a full-service moving company. These companies take all the hassle out of your move by disassembling and packing up your old house and then unpacking and reassembling everything in your new place. Additionally, they provide all of the materials so you don’t have to worry about how much tape you’ll need or what size boxes to get.

ALINA Residences

Alina Condominium, Boca Raton, FL

Alina Condominium, Boca Raton, FL

Alina Condominium, Boca Raton, FL

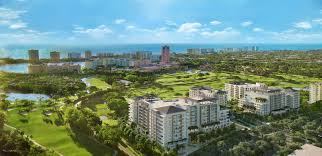
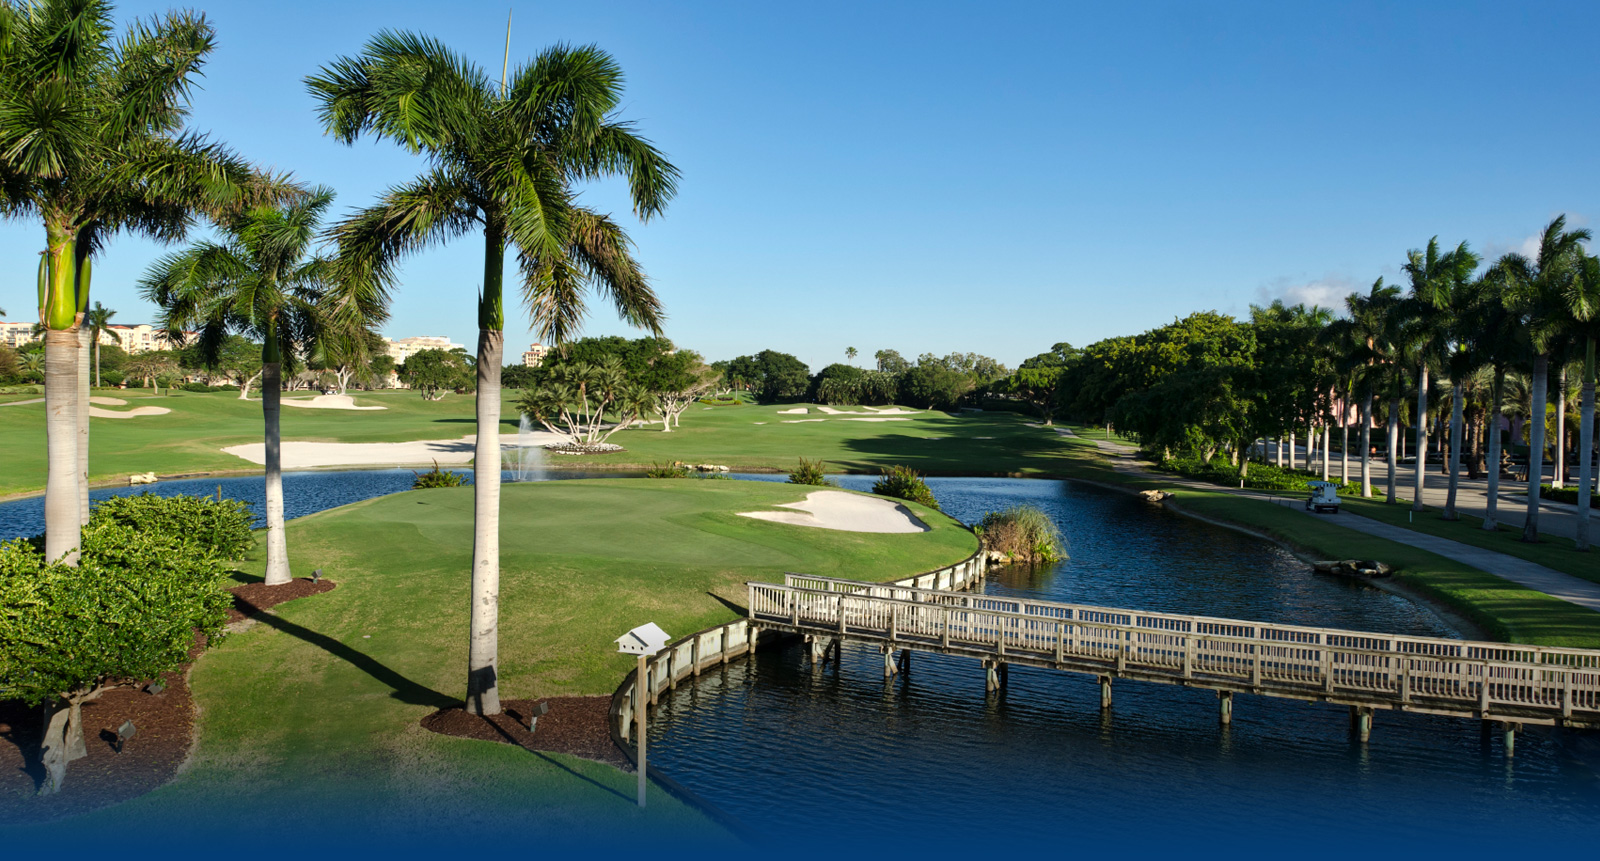
ALINA Residences is currently under construction on more than 8 acres on Southeast Mizner Boulevard in Downtown Boca Raton.  This luxury development is one of Palm Beach County’s latest new construction projects in South County.  The development will include a nine-story building with 121 condos, 102 of which will be fully furnished and 12 will be penthouses.  The units will range from one to four bedrooms ranging in size from 1400 to more than 4,800 square feet overlooking the Boca Raton Golf Club.  Alina will include seven villas with lanais and private gardens.

ALINA, designed by Garcia Stromberg and developed by El-Ad National Properties, will feature more than 32,000 square feet of residents-only outdoor amenities, a club room, fitness center, sauna, steam room, rooftop pool deck with cabanas and bike storage. ALINA’s landscaped outdoor promenades connect to the heart of Boca Raton, where Royal Palm Place, Mizner Park, al fresco dining, upscale galleries, and couture boutiques are all just a stroll away. Surrounded by nature in a peaceful resort atmosphere, ALINA is quietly tucked away in historic downtown Boca Raton, yet so close to a world of conveniences. Envelop yourself in the energy of downtown living, the captivating greenscape of the Boca Raton Resort and Club golf course, and the beauty of nearby beaches and fresh ocean breezes. This rich environment provides an abundance of options for active lifestyles and the opportunity for outdoor fitness and recreation.

View Residences  for Sale in ALINA below.  Call Kim Bregman at 561-251-7170 for a private showing.


This content is currently unavailable. Please check back later or contact the site's support team for more information.


Reasons to Buy in Florida Off Season

South Florida Real Estate for Sale

South Florida Real Estate for Sale

South Florida Real Estate for Sale


It’s cheaper, and sellers are serious!
The off season is Florida is typically the end of Easter/Passover through Thanksgiving.
Buying a home in the late Spring and Summer can be a thrifty move for homebuyers because it’s cheaper, sellers are ready, there are fewer choices, the buyer becomes the negotiator.
There’s typically less competition during the off season, which means buyers can get more bang for their buck. The four months with the lightest sales are June through September which means less competition as well.
Sellers are serious (or worn out) 
Whether a house has been on the market for months or the “for sale” sign has recently appeared in the yard, sellers tend to be serious during the off season. They are usually ready to make a deal, which means that buyers have more room for negotiation.
Buyers become the center of attention
During the winter months,real estate agents, mortgage lenders, title companies and other professionals tend to be swamped, which means that clients might not always get the attention they need or want. Once the summertime arrives buyers may receive more attention from the experts and experience fewer delays and service issues.
Buyers can catch some great sales to outfit their home
If your clients are in need of appliances or other items to help maintain or furnish their new home, then they’re sure to find some good deals during this time of the year.
According to Consumer Reports, it all depends on the month. In September, is furniture sale month and carpet and paint are usually on sale as well. October is a great time to purchase a lawn mower, and November tends to be the month for selecting new appliances and cookware.
Mortgage rates are at an all time low in the pas two years. Home affordability has increased this summer, but there is no telling when rates will start to rise again.

How To Invest Your IRA In Real Estate

IRA Investment Strategies

IRA Investment Strategies

IRA Investment Strategies

There are several advantages of using a self-directed IRA or Solo 401(k) plan to buy real estate. The first is tax deferral or tax-free growth. For example, if one purchased a piece of property with retirement funds for $80,000 and later sold the property for $300,000, the $220,000 of gain appreciation would generally be tax-deferred. Whereas, if you purchased the property using personal funds (non-retirement funds), the gain would be subject to federal income tax, and in most cases, state income tax. Second, a self-directed IRA can allow you to invest in hard assets you know and understand, such as a rental property or piece of land. Lastly, having the ability to invest in alternative assets is believed to be a good source of investment diversification.
Real Estate Investment Trusts (REITs)
If you are looking for easy transactions both in and out, REITs provide that. Many REITs are registered with the SEC and are publicly traded on a stock exchange. These are known as publicly traded REITs. Others may be registered with the SEC but are not publicly traded. These are known as non- traded REITs (also known as non-exchange traded REITs).
All REITs have their own specialties, so make sure you do your due diligence on the company. REITs are required to distribute 90% of its taxable income as dividends, so many retirees look to REITs for income.
Rental Properties
You can also invest in rental properties. You can buy distressed properties, rehabthem and rent them out or you can buy performing ones. If you decided that you want to go the distressed route you’ll have to keep a very close eye on the accounting. There are lots of rules in regards to tracking the money. You can either manage them on a daily basis or go through the process of hiring a property manager to manage it for you. This is a good way to build a passive income stream.
Turnkey Real Estate Investment
Turnkey is another viable option for SDIRA owners. Self-directed IRA (SDIRA) is another option for an IRA holder, which allows them to invest in diversified assets. To expand on “diversified assets,” this means that you aren’t restricted to stocks and bonds like most IRAs. You are able to invest in many different things. SDIRA serves as a savings account where your money can grow tax-free until you withdraw the funds, unless it is a Roth IRA. If it is a Roth IRA, the money is taxed prior to going into the account and when it is withdrawn, it is tax-free.
The owner simply transfers funds from his/her IRA or other retirement account to SDIRA. Many of them increase the amount invested with their personal contributions to the account.
A Turnkey Real Estate investment basically means that you are working with a turnkey investment company that are selling rental properties. Most of these investment properties are already rehabbed and rented out. You just need to buy the property and everything else in managed by the turnkey company. This is the best option for out-of-state investorsor someone who’s not interested in buying, rehabbing or managing the property. You’ll get the rent every month and you’ll pay a portion of that to your turnkey company for managing the properties. It is a easy hands off approach to investing in real estate.
Make sure to do your research properly in order to find the right turnkey investment company.Pay them a visit, check the property in person and invest once you’re satisfied.
You may have noticed that fix and flip is not on this list. And there is a big reason for that. The idea behind an IRA is that it is a retirement account, not a business account. If you start conducting business in your IRA, it can open you up to tax liabilities.

Tax Considerations When Deciding to Relocate.

Florida retains its ranking as one of the nation’s lowest-tax states, according to the latest study released by Florida TaxWatch. Out of 50 states, Florida ranks No. 42 in the average amount of money paid by residents.
Florida TaxWatch findings:
  • Floridians pay an average $5,679 per person in state and local taxes
  • Residents pay an average $2,584 in state taxes – one of the least amounts nationwide. Only the residents of one other state pay less.
  • However, local tax burdens are higher. “Per Capita Local Tax Collections” ranked No. 27 nationally.
  • In the balance between state and local taxes, Florida relies more heavily on local revenue than almost all other states and is No. 2 nationwide. Local taxes account for 53.3 percent of the total.
  • With property taxes, Florida ranks a solid “average” score – No. 25. The state’s per capita property tax ranking is right at the median – 25th.
  • Florida also classifies 38.7 percent of its state and local revenue as non-tax revenue (such as “fees”) – the 7th largest percentage in the nation.
  • Florida relies more heavily on transaction taxes, such as general and sales taxes. They make up, 81.5 percent of all state tax collections compared to the national average of 47.2 percent.
  • Florida has the highest state and local selective sales (excise) taxes on utilities in the nation. The tax on motor fuels is No. 15; the tax on alcoholic beverages is No. 19.
  • Florida’s housing sector produces significant revenue, and the state’s documentary stamp taxes are rising rapidly post-recession. It collected an average of $276 per capita in 2006, $72 in 2009, and $130 per capita in 2016 – the nation’s second-largest doc-tax burden.
  • Florida is one of seven states without a personal income tax. The average state relies on personal income taxes for 37.0 percent of its tax revenue.
  • Businesses pay 51.7 percent of all Florida state and local taxes – the 12th highest percentage in the nation.