Slide 1

South Florida’s Exclusive Buyers Agent

Slide 2
For over 40 years

Exclusive Buyer Agency

Cash vs. Financed Offers: What Buyers Should Know
FAR/BAR As Is Contract

With the Florida Realtors/Florida Bar “As Is” Residential Contract for Sale, choosing between a cash offer and a financed offer changes how risky your offer looks to the seller, how quickly you can close, and which exits you keep under the contract as a Buyer. This guide explains how each option works so you can decide which fits your situation and your goals for the purchase.

Cash Offer:

  • Fewer outs for the buyer. There is no loan or appraisal contingency, so the main ways to cancel are the inspection period and any addenda added.
  • Seller appeal. Sellers often favor cash because there is less risk of a deal falling apart over financing.
  • Faster closing. With no lender involved, closing can often happen sooner.
  • Proof of funds. Expect to provide a bank or brokerage or bank statements showing you have the funds for the purchase price plus closing costs.
  • Inspection rights stay. Under the As Is contract, a cash buyer still has the inspection period. Cash does not mean giving up your right to inspect.
  • Buying through an LLC or trust? There are new federal FinCEN reporting rules for certain cash purchases.

Financed Offer:

  • Loan approval contingency. The contract sets deadlines for applying for and obtaining loan approval. If your loan is denied within the contingency window, you can generally cancel and recover your deposit. Confirm the exact deadlines in your contract.
  • Appraisal risk. If the home appraises below the price, you may need to renegotiate, pay the difference in cash, or cancel under the contract’s terms.
  • Longer timeline. Closing often takes 30 to 45 days.
  • Lender requirements. Some loans, especially FHA and VA, may require repairs. Under an As Is contract the seller is not obligated to make them, so plan for that negotiation.

Making a Financed Offer Stronger:

  1. Provide a full lender pre-approval letter, not just a pre-qualification.
  2. Offer a larger deposit.
  3. Shorten the loan approval and inspection periods if you are comfortable doing so.
  4. Consider covering an appraisal gap, only if you can afford the difference.
  5. Work with a lender known for closing on time.

Bottom Line:

Neither approach is better for every buyer. Cash offers are simpler and often more attractive to sellers, while a well-prepared financed offer can still compete when it is backed by a strong pre-approval, a solid deposit, and realistic deadlines. Talk through your finances and risk tolerance with your agent and lender before you write an offer, and have a Florida real estate attorney review your contract.  This overview is general information, not legal or financial advice.
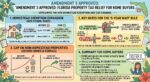
Florida’s Amendment 3: What Homebuyers Need to Know!

Florida voters approved Amendment 3 in November 2026, expanding homestead exemption rules beginning in 2027. The changes may affect primary-home buyers, investors, and people moving to Florida.

1. Larger tax savings for primary homes

For homesteaded primary residences, the amount of assessed value exempt from non-school property taxes (city, county, and special district levies) increases in stages:

  • 2026 baseline: up to about $50,000 exempt from non-school taxes.
  • 2027: the first $150,000 of assessed value is exempt.
  • 2028: the first $250,000 is exempt.
  • 2029 onward: the $250,000 cap adjusts annually for inflation.

That can lower annual tax bills. Starting in 2028, homes assessed below $250,000 may owe no non-school property taxes. School district taxes are not affected; they account for roughly 40% of a standard tax bill and retain the baseline $25,000 exemption.

2. When you establish Florida residency matters

People who establish Florida residency on or before December 31, 2026, can qualify for the full expanded exemption as soon as they buy and homestead a primary residence. People moving to Florida on or after January 1, 2027, generally receive the existing exemption first and must wait five years to access the higher $150,000 and $250,000 tiers, unless their county or municipality shortens the wait.

3. A lower assessment-growth cap for other properties

Vacation homes, rentals, and commercial properties do not qualify for the expanded primary-home exemption. Starting January 1, 2027, however, the annual assessment-growth cap for non-homestead properties is cut from 10% to 5% for non-school taxes. This can make holding costs more predictable when property values rise quickly.

4. Local fees and services may change

Removing taxable value from local rolls may reduce county and municipal revenues. Local governments could respond with higher non-property fees or utility rates, changes to millage rates, or reductions in some maintenance and public services.

Amendment 3 may make Florida homeownership more attractive, but the benefit depends on when you establish residency and whether the property is your primary home or an investment. If you are relocating, timing matters: current Florida residents may qualify beginning in 2027, while many new residents will wait until their fifth year of homestead eligibility for the expanded benefit.

Understanding the rules before you buy can help you make a more informed financial decision. If you’re considering a Florida home, contact me today to discuss your timeline and take the next step before the 2027 changes begin.

Buying a Home With Solar Panels? Ask These Questions First.

Solar Panels

Solar panels and battery backup systems are becoming increasingly common on Florida homes. But if you’re buying a home with solar, there is an important piece of due diligence that shouldn’t be overlooked.

I recently experienced this firsthand when a client was purchasing a home with Tesla solar panels and a backup battery system. It required learning not only about the technology, but also about the financial and contractual obligations that can come with it.

Who Owns the Solar Panels?

Before entering into a contract, buyers should determine whether the solar system is:

  • Owned outright
  • Financed
  • Leased

This distinction matters because solar panels are generally considered fixtures and may be included with the property. However, financing or lease obligations may need to be paid off, transferred, or otherwise addressed before closing.

Under the Florida Realtors/Florida Bar Residential Contract for Sale and Purchase, as well as the “AS IS” version, the real property conveyed to the buyers generally includes existing improvements and fixture unless specifically excluded from the contact.

If the System Is Financed or Leased

Don’t assume that financing or a lease can simply be transferred to the buyer. The solar company or lender may not permit an assumption, and there may be additional requirements or fees. In some cases, mortgage lenders may also require certain financing to be satisfied or released before closing.

If the panels are leased, early termination can also be complicated or expensive because leases may extend for many years.

My Advice to Buyers

Ask about the solar system early—preferably during the Inspection Period—and obtain copies of all financing, lease, warranty and service documents.

If a transfer of a lease or assumption of solar financing is involved, I strongly advise getting an attorney involved before proceeding. This is one situation where understanding the obligations before you commit can save you from an unexpected problem at closing.

🚩 RED FLAG

Seller says, “The solar company will just transfer it to you.”

Don’t take that for granted. Confirm directly with the solar company or lender whether the lease or financing can actually be transferred, what the requirements are, and whether your mortgage lender will permit it.

Bottom line: Solar panels may be a great feature, but make sure you know exactly what comes with them before you buy the house.

Beyond the Purchase Price… Real Costs of Owning a Luxury Home

Buying a luxury home in South Florida is about much more than finding the right location, architectural style, or view. Whether you are considering a waterfront estate, a golf community residence, or a luxury condominium, the purchase price is only one part of the financial picture. Before making an offer, today’s sophisticated buyer should understand the true cost of ownership. Planning ahead can help avoid surprises and ensure that your new home fits comfortably within your long-term lifestyle and financial goals.

1. Insurance Can Be a Significant Expense

Insurance is one of the first expenses luxury buyers should investigate—before the inspection period is over. The cost of homeowners, windstorm and, when applicable, flood insurance can vary dramatically based on a property’s location, age, construction and protective features.The age and condition of the roof, impact-resistant windows and doors, elevation, prior claims history and proximity to the coast can all affect coverage and premiums.

2. Property Taxes – May Differ Signifcantly After the Sale

A common mistake is assuming that the seller’s current property tax bill will be the same after you purchase the home. In Florida, a property’s assessed value and tax benefits can change following a sale. A home may appear to have relatively low property taxes simply because the current owner has benefited from assessment limitations or exemptions that may not transfer to the new owner.

3. Waterfront Living Comes With Additional Responsibilities

There is nothing quite like living on the water in South Florida—but waterfront ownership may involve additional expenses and maintenance.

Depending on the property, buyers may need to budget for the maintenance and eventual replacement of:

  • Seawalls
  • Docks
  • Boat lifts
  • Pilings
  • Waterfront landscaping
  • Irrigation systems
  • Pools and outdoor entertainment areas

Before purchasing, it is important to understand the age and condition of these improvements. Replacing or repairing waterfront infrastructure can be a substantial investment.

4. Luxury Homes Require Specialized Maintenance

A larger, more sophisticated home typically comes with more systems to maintain. The true cost of ownership may include regular service for:

  • Multiple air-conditioning systems
  • Swimming pools and spas
  • Generators
  • Elevators
  • Smart-home technology
  • Security and surveillance systems
  • Water treatment systems
  • Extensive landscaping and outdoor lighting

For a luxury estate, it may also be appropriate to budget for a property manager, housekeeper, pool service or landscaping team.

5. The Inspection Should Go Beyond the Basics

A standard home inspection is important, but a luxury property may warrant additional specialists. Buyers may want specialied inspections of the roof, pool, dock, seawall, elevator, generator, HVAC systems, plumbing, electrical systems and smart-home equipment. Waterfront properties may require particularly careful evaluation of marine structures and drainage.

6. Condominium Buyers Need to Look Beyond Monthly Fees

For luxury condominium buyers, the monthly association fee is only part of the equation. Buyers should carefully review the building’s financial condition, reserves, planned maintenance and any pending or potential special assessments.

7. Climate Resilience Can Affect Both Cost and Value

Today’s South Florida luxury buyer is increasingly focused on how a home is built and protected. Features such as impact glass, a newer roof, a whole-house generator, appropriate drainage and modern construction standards can affect not only day-to-day peace of mind but potentially insurance availability, maintenance costs and future marketability.

The Bottom Line

The right luxury home should enhance your lifestyle—not create unexpected financial surprises.In South Florida’s luxury market, knowledge is a valuable asset. The more thoroughly you understand a property before you buy, the more confidently you can make a decision—and the better prepared you will be to enjoy the exceptional lifestyle that luxury homeownership can offer.

Thinking about buying a luxury home in South Florida? Before you make an offer, let us help you evaluate not only the home itself, but also the factors that can affect its long-term cost, value and enjoyment.

Build vs Buy

Build vs Buy

One of the biggest decisions homebuyers face is whether to purchase a brand-new build or an existing home. Each path offers distinct financial, lifestyle, and logistical trade-offs, and the right choice depends on your timeline, budget, and long-term priorities.

New Construction Homes

The Pros

  • Everything is brand new: From the roof and HVAC system to appliances and flooring, new builds require minimal maintenance during the first several years.
  • Modern energy efficiency: Newer homes adhere to updated building codes and incorporate modern insulation, high-efficiency windows, and advanced HVAC systems, which can significantly lower monthly utility bills.
  • Personalization and customization: Depending on when you purchase during the construction phase, you can often select your floor plan, finishes, cabinetry, countertops, and tech integrations before moving in.
  • Builder warranties: Most builders offer structured warranties (often covering cosmetic defects for 1-year, mechanical systems for 2 years, and structural elements for up to 10 years), providing extra peace of mind.
  • Financial incentives: Builders frequently partner with preferred lenders to offer rate buy-downs, closing cost credits, or design-center allowances that reduce upfront cash needs.
  • Lower initial insurance premiums. Homeowners insurance is generally lower for new builds because all structural elements, roofing, plumbing, and electrical systems are brand-new and built to modern safety and building codes.

The Cons

  • Higher price per square foot: New homes usually command a premium over comparable existing homes in the same general area.
  • Upgrade costs add up: Model homes feature high-end finishes that aren’t included in the base price. Essential items like window blinds, pools, fencing, and fixtures often have to be paid for out-of-pocket after closing.
  • Construction delays & uncertain timelines: Supply chain bottlenecks, weather, or labor shortages can push back your completion date, making it tricky to align lease endings or existing home sales.
  • Developing surroundings: You may live in an active construction zone for month, complete with heavy machinery, dust, immature landscaping and a period without amenities.
  • Construction phase coverage needs. If you build custom or purchase early in the build process, standard homeowners’ insurance won’t apply until completion, requiring specialized builder’s risk policies during construction.
  • Uncertain initial property taxes and HO fees: Property taxes on new builds are initially assessed on the unimproved land value and will increase significantly once the home is fully built and reassessed.  HOA costs ae covered by the developer until such time as it transitions to the Homeowners Association.  Decisions made by the HOA can increase the fees over time.

Existing Homes

The Pros

  • Established locations and character: Existing homes are often situated in mature neighborhoods with tree-lined streets, established school districts, and closer proximity to urban centers, dining, and shopping.
  • Immediate move-in: Once your mortgage is cleared and escrow closes—typically in 30 to 45 days—you can move right in without construction delays.
  • Larger lots and architectural variety: Older neighborhoods frequently offer larger lot sizes, setback distances, and distinct architectural features compared to uniform modern subdivisions.
  • Greater negotiation power: Unlike builders who resist lowering base prices to protect neighborhood appraisal values, individual sellers may negotiate on price, request repairs, or grant seller concessions.
  • Established claims & risk history. Existing properties have clear, predictable history and records that allow insurance carriers to assess baseline risk quickly.

The Cons

  • Maintenance and deferred repairs: Major systems like the roof, plumbing, electrical, or HVAC may be near the end of their lifespan, requiring short-term capital outlay.
  • Higher ongoing energy costs: Older insulation, windows, and aged appliances can lead to higher utility bills.
  • Costly renovations: Modernizing a floor plan, opening walls, or updating kitchens and baths requires significant time, budget, and oversight.
  • Higher premiums & insurability challenges. Older roofs, outdated wiring (like knob-and-tube or aluminum), galvanized plumbing, or aged heating systems can make premiums significantly higher—or require costly mandatory repairs before a carrier agrees to issue coverage.

To narrow down your decision, consider where you fall on these core priorities:

Decision Factor Leaning Toward New Construction Leaning Toward Existing Home
Move-in Date Flexible (willing to wait 6–12+ months) Urgent (need to move within 30–60 days)
Maintenance Comfort Prefer a turn-key home with zero DIY projects Comfortable handling repairs or remodeling over time
Location & Lot Size Prefer master-planned communities, modern amenities Prefer central locations, larger yards, mature trees
Upfront Costs Prefer builder financing incentives and buy-downs Prefer lower base purchase price per square foot
Insurance Lower initial insurance costs Insurance may be an issue if financing

2026 Hurricane Preparedness Guide

2026 Hurricane Season

2026 Hurricane Season

2026 Hurricane Preparedness Guide
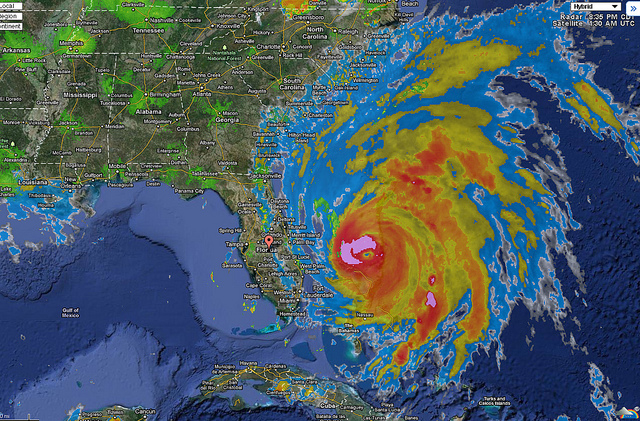
The 2026 hurricane season is fast approaching. NOAA’s outlook for the 2026 Atlantic hurricane season, which runs June 1 to November 30, predicts a 35% chance of a near-normal season, a 10% chance of an above-normal season, and a 55% chance of a below-normal season. The agency is forecasting a total of 8-14 named storms (winds of 39 mph or higher).and it looks to be another active one. At least 40% of the hurricanes that happen in the United States occur in Florida.

In order to ensure you are properly prepared this hurricane season, you should consider how you are going to supply your homes given that hurricane season begins June 1st. Don’t be caught unaware, protect yourself.

Hurricane hazards come in many forms, including storm surge, high winds, tornadoes, and flooding. History teaches that a lack of hurricane awareness and preparation are common threads among all major hurricane disasters. By knowing your vulnerability and what actions you should take, you can reduce the effects of a hurricane disaster.

Know Hurricane Terms:

Hurricane Watch – A hurricane is possible within thirty-six hours. Stay tuned for additional information.
Hurricane Warning – A hurricane is expected within twenty-four hours. You may be advised to evacuate. If so, evacuate immediately.
Storm Surge – Storm surge is simply water that is pushed toward the shore by the force of the winds swirling around the storm. This advancing surge combines with the normal tides to create the hurricane storm tide, which can increase the mean water level 15 feet or more.
Ask your local emergency preparedness office about evacuation plans. Learn evacuation routes.
  • Plan a place to meet your family in case you are separated from one another in the hurricane.
  • Assemble a disaster supplies kit ( See information below)
  • Board up windows. Permanent storm shutters and impact glass offer the best protection. Also, you can use 5/8″ marine plywood. Tape does not prevent windows from breaking.
  • Know how to shut off utilities.
  • Make a record of your personal property (take digital photos or video tape the contents of your home and/or business and keep in a waterproof container with you along with your homeowners insurance policy or better yet, upload everything to the Cloud)
  • Be sure trees and shrubs around your home are well trimmed.
  • Clear loose and clogged rain gutters and downspouts.
  • Determine how and where to secure your boat.
  • Reduce the water level in your pool by about 1 foot. DO NOT drain your pool.
  • Charge cell phones and back up batteries
  • Get extra cash since ATMs will be inoperative if power is lost.
  • Consider flood insurance and purchase it well in advance.

Have a Place To Go:

Develop a family hurricane preparedness plan before an actual storm threatens your area. If your family hurricane preparedness plan includes evacuation to a safer location for any of the reasons specified with in this web site, then it is important to consider the following points:
If ordered to evacuate, do not wait or delay your departure.
If possible, leave before local officials issue an evacuation order for your area. Even a slight delay in starting your evacuation will result in significantly longer travel times as traffic congestion and weather deteriorates worsens.
Select an evacuation destination that is nearest to your home, preferably in the same county, or at least minimize the distance over which you must travel in order to reach your intended shelter location. In choosing your destination, keep in mind that the hotels and other sheltering options in most inland metropolitan areas are likely to be filled very quickly in a large, multi-county hurricane evacuation event.
If you decide to evacuate to another county or region, be prepared to wait in traffic.
The large number of people in this state who must evacuate during a hurricane will probably cause massive delays and major congestion along most designated evacuation routes; the larger the storm, the greater the probability of traffic jams and extended travel times.
If possible, make arrangements to stay with the friend or relative who resides closest to your home and who will not have to evacuate. Discuss with your intended host the details of your family evacuation plan well before the beginning of the hurricane season.
If a hotel or motel is your final intended destination during an evacuation, make reservations before you leave. Most hotel and motels will fill quickly once evacuations begin. The longer you wait to make reservations, even if an official evacuation order has not been issued for your area or county, the less likely you are to find hotel/motel room vacancies, especially along interstate highways and in major metropolitan areas.
If you are unable to stay with friends or family and no hotels/motels rooms are available, then as a last resort go to a shelter. Remember, shelters are not designed for comfort and do not usually accept pets. Bring your disaster supply kit with you to the shelter. Find Pet-Friendly hotels and motels.
Make sure that you fill up your car with gas, before you leave.

Preparing Your Pets for Emergencies Makes Sense.

If you are like millions of animal owners nationwide, your pet is an important member of your household. The likelihood that you and your animals will survive an emergency such as a fire or flood, tornado or hurricane depends largely on emergency planning done today. Some of the things you can do to prepare for the unexpected, such as assembling an animal emergency supply kit and developing a pet care buddy system, are the same for any emergency. Whether you decide to stay put in an emergency or evacuate to a safer location, you will need to make plans in advance for your pets. Keep in mind that what’s best for you is typically what’s best for your animals.
If you must evacuate, take your pets with you if possible. However, if you are going to a public shelter, it is important to understand that animals may not be allowed inside. Plan in advance for shelter alternatives that will work for both you and your pets.
Make a back-up emergency plan in case you can’t care for your animals yourself. Develop a buddy system with neighbors, friends and relatives to make sure that someone is available to care for or evacuate your pets if you are unable to do so. Be prepared to improvise and use what you have on hand to make it on your own for at least three days, maybe longer.

Disaster Supply Kit

I personally prepare a hurricane closet in May with all the needed supplies and materials so that there is never a last minute rush to the store when the shelves have been cleaned out.
Water :
  • Plan on one gallon of water per person per day for at least 3 days, for drinking, washing, cooking, and sanitation. Extra water for pets
  • Store as much as possible in plastic containers such as soft drink bottles.
  • Avoid using breakable containers, such as glass bottles or mason jars.
  • Fill bathtubs with water for bathing and washing dishes
Food :
  • Store at least a three day supply of non perishable food.
  • Choose foods that do not require refrigeration or cooking.
  • Choose foods that are healthy and high nutrition type.  (Canned meats, fruits and vegetables, protein or fruit bars, dry cereal or granola, peanut butter, dried fruit, nuts, crackers, canned juices, non-perishable pasteurized milk, high enery foods, vitamins, food for infants and pets, comfort/stress foods)
Supplies and Equipment:
  • A battery operated radio with extra batteries
  • NOAA Weather Radio with tone alert and extra batteries
  • A flashlight with extra batteries
  • Blankets or sleeping bags ( store in trash bags to keep dry)
  • Paper plates and utensils, including a non electric can opener
  • Candles and matches in a waterproof container
  • Plastic sheeting and duct tape to shelter-in-place
  • Toothbrushes, toothpaste, soap, moist towelettes, and other personal grooming items
  • Paper towels and toilet paper
  • First aid kit and medicines ( ask your pharmacist or drug supply company for a one month hurricane supply and store in water proof container)
  • Fire extinguisher
  • Wrench or pliers to turn off utilities
  • Cell phone and plug in battery operated charger
  • Infant formula and diapers
  • Books, games and toys to keep kids occupied ( remember those batteries)
  • Important family documents such as copies of insurance policies, identification and bank account records, COVID Vaccine Passport, in a waterproof, portable container
  • Complete change of clothing including long sleeved shirt, long pants and sturdy shoes
  • Insect repellent and sun-screen
  • Paper and pencil
  • Local Maps
  • Make sure to keep all of your medications filled.

Business Preparedness

* Have an emergency communication plan in place before the storm hits. How will co-workers stay in contact if the physical location of a business is damaged?
* Turn off all non-critical work devices before the storm hits.
* Alert a third party about business evacuation plans in case a storm makes it impossible to get to your place of business.
* Protect important business documents that you may need quickly, such as property insurance policies.
* Have cash on hand to pay employees or contractors after the storm.
* Know which employees are certified in CPR, EMT, etc.
* If possible, disconnect a building’s main electrical feeds.
* Have a plan to notify all employees, post-storm, about damage and how you’ll move forward.
* Review contracts that are date sensitive and have a backup plan in place to handle potential problems.
* Assess all functions that could be impacted by a lapse in business – cash flow, bills, budgets and any upcoming events.

Pros and Cons of Buying A Fixer-Upper

Buying a fixer-upper offers pros like lower purchase prices, less competition, and total customization for building equity, but comes with significant cons including hidden costs, major time commitments, unexpected problems (like bad wiring), and lifestyle disruptions from living through renovations, requiring deep pockets and patience to succeed. It’s a great investment if planned well but can become a “money pit” if you underestimate the work or skip due diligence like inspections.

A fixer-upper is best for those with patience, a strong budget buffer, DIY skills (or money for contractors), and a clear vision, especially if you can live in a partially completed home.

Pros of Buying a Fixer-Upper

  • Lower Purchase Price: Fixer-uppers typically cost 10% to 30% less than move-in-ready homes in the same area. This translates to a smaller down payment and lower monthly mortgage costs initially.
  • Access to Prime Locations: You can often afford the “worst house on the best neighborhood,” allowing you to move into desirable areas with top schools or transit that would otherwise be priced out of your budget.
  • Forced Equity: By improving the property, you can significantly increase its market value. If managed correctly, the final value of the renovated home can exceed your total investment (purchase price + renovation costs), building wealth quickly.
  • Full Personalization: Unlike move-in-ready homes where you pay for someone else’s style, a fixer-upper allows you to choose every finish—from the layout and flooring to the kitchen cabinetry—to match your exact taste.
  • Less Competition: Most buyers prefer “turnkey” properties, meaning have more leverage to negotiate the price or repair credits.

Cons of Buying a Fixer-Upper

  • Unexpected “Hidden” Costs: Even with a thorough inspection, opening walls can reveal expensive surprises like mold, outdated wiring, or structural issues. Experts recommend a 10% to 20% contingency fund for these surprises.
  • Complex Financing: Standard mortgages often won’t cover renovation costs. You may need specialized products like an FHA 203(k) loan or a Fannie Mae HomeStyle loan, which have stricter requirements and deadlines.
  • Timeline Disruptions: Renovations rarely finish on time. Delays from material shortages, contractor schedules, weather, or permit approvals can push your move-in date by months.
  • Lifestyle Impact: Living in a construction zone—dealing with dust, noise, and no functional kitchen—can be extremely stressful. If you choose to live elsewhere during work, you must budget for double housing costs (mortgage + rent/hotel).
  • Risk of Over-Improvement: If you spend more on renovations than the neighborhood’s ceiling value, you may struggle to recoup your investment when you eventually sell.

2026 Strategic Considerations

  • Tax Reassessments: Florida law requires that qualifying home improvements be assessed at their full market value as of January 1 following substantial completion. This means that the “Save Our Homes” (SOH) assessment cap, which limits annual increases on homesteaded properties to 3% or the Consumer Price Index (CPI), does not apply to the value of new construction or additions. To understand how a specific project might affect your property taxes, you should contact your local county property appraiser’s office, as standards can vary slightly by county.
  • Energy Credits: Look for federal or state tax credits for energy-efficient upgrades (e.g., heat pumps, solar, or insulation) to help offset costs.

The key is running your specific numbers with clear eyes, being honest about your cash reserves and available time, and understanding that sweat equity is real equity only if you actually have the skills, resources, and bandwidth to see it through.

June Key Home Buying Trends

3621 South Ocean Town Homes for Sale in Highland Beach, Florida

Florida Consumer Sentiment Climbs Again

Economic sentiment rose 3.1 points to 84.1 in June, with all five index components improving. The biggest gains were in views of personal finances.

Two New Property Insurers Approved

Two more property insurers have been approved to operate in Florida, bringing the total to 14 since recent reforms. Officials say the market is stabilizing.

Florida Sees Surge in Commercial Real Estate

Fueled by population gains, tax advantages and a strong economy, commercial real estate investment is rising across the state, experts say.

Florida Leads in International Home Sales

International buyers purchased 78,100 U.S. homes over 12 months, reflecting a 33.2% jump from the year before and the first increase since 2017.

Luxury Market Stronger Than Ever

Industry leaders say the high-end market, particularly for homes priced above $10M, is continuing to gain strength, with all-cash deals the norm.

Florida Sees Shift in New-Home Prices

Florida is among the top states seeing new construction price declines, creating potential opportunities for buyers as builders adjust to market conditions.

Florida Ranks High Among 2025 Movers

Florida continues to attract new residents, particularly Baby Boomers, in 2025, thanks to warm weather, no income tax and affordability.

Mortgage Giants to Count Crypto as Asset

Homebuyers may soon be able to use crypto as part of their mortgage qualifications, under a new order for federally backed loan programs.

Insurance Reforms Stabilizing Florida Market

A Florida consumer group says recent reforms have reduced litigation, lowered Citizens’ policies and attracted new insurers, helping stabilize the market.

Rate, Home Price Growth Forecasts Lowered

Fannie Mae now sees slower home price growth and slightly lower mortgage rates through 2026, with modest gains expected in overall home sales.

U.S. Home Prices Down 0.2% in May

The FHFA said prices are up 2.8% from last year across the United States. In the South Atlantic census division, which includes Florida, home prices increased 1.4%.

U.S. Consumer Confidence Improves in July

Americans remain concerned about tariffs, but confidence rose two points to 97.2 in July, up from 95.2 the previous month.

New Home Construction Advice

New Construction Assistance

It’s important to understand when buying new construction,  that the builder’s agent is primarily focused on securing the best deal for the builder, often at the expense of the homebuyer. Their role is to persuade you to purchase their homes at the highest price with minimal concessions. In contrast, as your Exclusive Buyer Agent, Optima Properties is dedicated to leveling the playing field.

Our mission is to advocate for your best interests, ensuring that you receive the best possible terms for your home purchase. We are here to negotiate on your behalf, providing you with the knowledge and strategies necessary to navigate this complex process with confidence. While the builder’s agent is legally bound to represent the builder, we prioritize your needs and work tirelessly to make your home buying experience smooth and enjoyable.

Benefits of Using an Exclusive Buyer Agent for New Construction:

  1.  Compare and evaluate builders’ reputations and history of their construction quality and service
  2. Help you compare and evaluate advantages and disadvantages of new construction homes vs. resale homes
  3. Provide information about the community and compare and contrast with other new construction communities
  4. Help buyer evaluate which options should be done by the developer during construction and which are more affordable to be done by an outside vendor post-closing.
  5. Assist with design and structural selections that will optimize future resale value and livability.
  6. Assist buyer evaluate the selection of a building lot and options. Lot location and certain options have a direct correlation to resale value.
  7. Truly negotiate on behalf of the buyer. Many builders are offering “free” options and upgrades, but some are also making additional price concessions.
  8. Review the Agreement of Sale (PA) prior to buyer signing. This is not a legal review (only an attorney can do that), but an experienced agent will be able to spot terms and conditions that are atypical and of potential concern to the buyer. The agent may then be able to negotiate terms and conditions that are more favorable to the buyer but still acceptable to the builder. Keep in mind most new construction contracts are written by attorneys that represent the developer and these contracts are therefore heavily weighted in favor of the builder.
  9. Recommend a real estate attorney for final contract, title commitment and to hold your escrow funds.
  10. A buyer’s agent serves as an extra set of ears as a witness at court or arbitration – When the builders sales representative is familiar with all rules, features and prices and it’s all new to buyer – it is good to have experienced person on buyer’s side listening with buyer and taking notes, a lot of information is verbalized in short period of time.
  11. Attend the signing of the Agreement of Sale
  12. Assist with the buyer’s financing and review financing paperwork. This is especially important if the builder is tying “free” options and upgrades to the use of a builder-affiliated lender.
  13. Check on the property during construction and keep a photo record at different stages.
  14. Be your leverage with the builder as problems arise during construction
  15. Keep everything in writing – Sometimes even the very nicest builder makes verbal promises that later become a point of contention. An experienced buyer’s agent is conditioned and trained to “put it in writing” even though at the time it doesn’t seem necessary.
  16. Arrange for a final inspection with a license building inspector and generate a “punch list” to be completed before final closing.
  17. Document and help resolve any issues with construction, financing, title, etc. throughout the process.
  18. Attend a pre-settlement walkthrough with the buyer to make sure that all items are satisfactorily completed or that a proper punch list is established to assure completion after settlement
  19. Obtain and review a preliminary HUD-1 settlement statement to be sure it is accurate and advise the buyer of the amount needed for settlement.
  20. Assist buyer with utilities, insurance, security and HOA requirements, decorators, service professionals, schools, et. al.
  21. Attend final walk-through and settlement with the buyer.
  22. A buyer’s agent will be there even after the home closes. It is routine for issues to arise during the first year of a new home. Site agents tend to forget a buyer’s name after the contract is signed.

But it’s important to remember the process of working with a builder is different than buying from a homeowner. And, while builders typically have sales agents on-site, having your own agent helps make sure you have proper representation throughout your home buying journey.